Devpost
Participate in our public hackathons
Devpost for Teams
Access your company's private hackathons
Grow your developer ecosystem and promote your platform
Drive innovation, collaboration, and retention within your organization
By use case
Blog
Insights into hackathon planning and participation
Customer stories
Inspiration from peers and other industry leaders
Planning guides
Best practices for planning online and in-person hackathons
Webinars & events
Upcoming events and on-demand recordings
Help desk
Common questions and support documentation
Fear makes people sell at any price. We show the patient buyer on the other side gets paid most when fear peaks, and we report every test we ran, including the ones that failed.
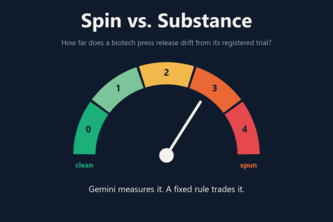
We use Gemini to read biotech trial press releases against the endpoint each company registered beforehand, and trade the gap between spin and substance.
Backfill turns FDA drug shortages into trading signals by identifying publicly listed competitors positioned to fill the supply gaps left by disrupted manufacturers.
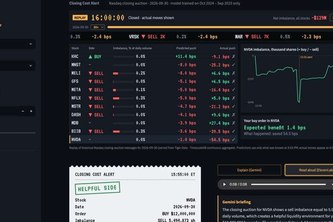
The closing push is real, but it's a cost, not a profit; so, we built a tool to warn funds before they pay it.
Pricing the Buildout tests whether infrastructure-company disclosures contain equity signals—and whether they survive point-in-time controls, transaction costs, and risk analysis.
PRISM (Price Reaction & Impulse Signal Model) is a cryptocurrency trading strategy designed to capture price continuation after unusual market movements with four-hour time resolution.
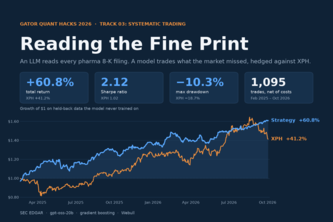
An LLM reads every pharma 8-K the minute it's filed and trades the stock against XPH. Out of sample it returned +61% with Sharpe 2.1 and almost no market beta.
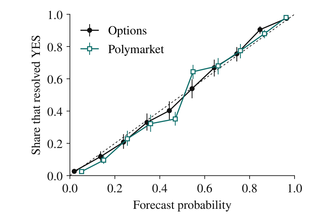
Option prices forecast Polymarket stock contracts 11% more accurately than Polymarket. PolyBridge measures the gap and trades only signals that pass tests written in advance.
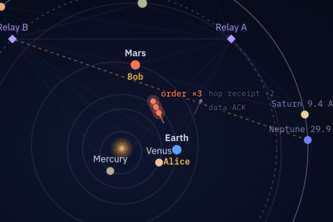
An exchange that works across light-minute delay. Every asset sits on one home ledger, deals lock then commit, and price contracts settle on a signed print, so no balance is ever lost or double-spent.
We present a prefunded design for trading equities and a capped futures contract across the nine settlements of the MultiPlanetary Exchange System.
We tested if investors overpay for puts after surprise leadership 8-Ks. Pre-registered, net of costs, on 2024–26 data: selling puts after fresh filings did worse than ordinary days.
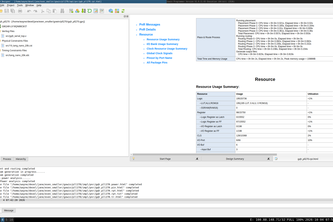
Optimized FPGA Calculations to BRAM
we r whale watchers & we luuuv mispricing & we luuuuv small-cap biotechs
We tested cattle economics as a trading signal in futures and stocks. Both strategies failed registered tests, producing an auditable study of net performance, execution risk, and funding constraints.
Data-is-all-you-need!
A trading bot on a tiny FPGA. It reads two prices over serial, tracks a moving average for each, and says BUY or SELL. Written in OCaml and squeezed into 195 logic cells.
We use Massive’s corporate disclosures to test when selling calls or buying puts adds value. HiPerGator runs the backtests; early results remain inconclusive.
A GPU genetic algorithm evolves which order-book signals XGBoost uses to predict whether bursts of aggressive trading in S&P 500 futures will snap back, net of trading costs.
The crypto space is no stranger to hacks. We tested if stolen funds fleeing into Monero move its price. Pre-registered, out-of-sample, net of costs. Verdict: the thieves launder, the market shrugs.
Can prediction markets tell you when to sell CPI-day options? We pre-registered the test on Solana, ran it on 50 releases, and found they can't: the premium looks like fair pay for tail risk.
This project implements a highly optimized, hardware-accelerated 16-sample moving-average trading algorithm for the Gator Quant Hacks Hardware Track.
MORTIMER is a six-asset equal-risk-contribution (ERC) strategy that dynamically scales exposure to forecast volatility, delivering systematic downside-risk mitigation with low return drag after costs.
We’re testing whether combining price trends, portfolio risk controls, and climate information can improve futures trading—and whether ENSO adds value beyond momentum alone.
Late executive 8-Ks, old news vs. surprise: a test of whether options overprice yesterday's news, committed before the data.
1 – 24 of 54